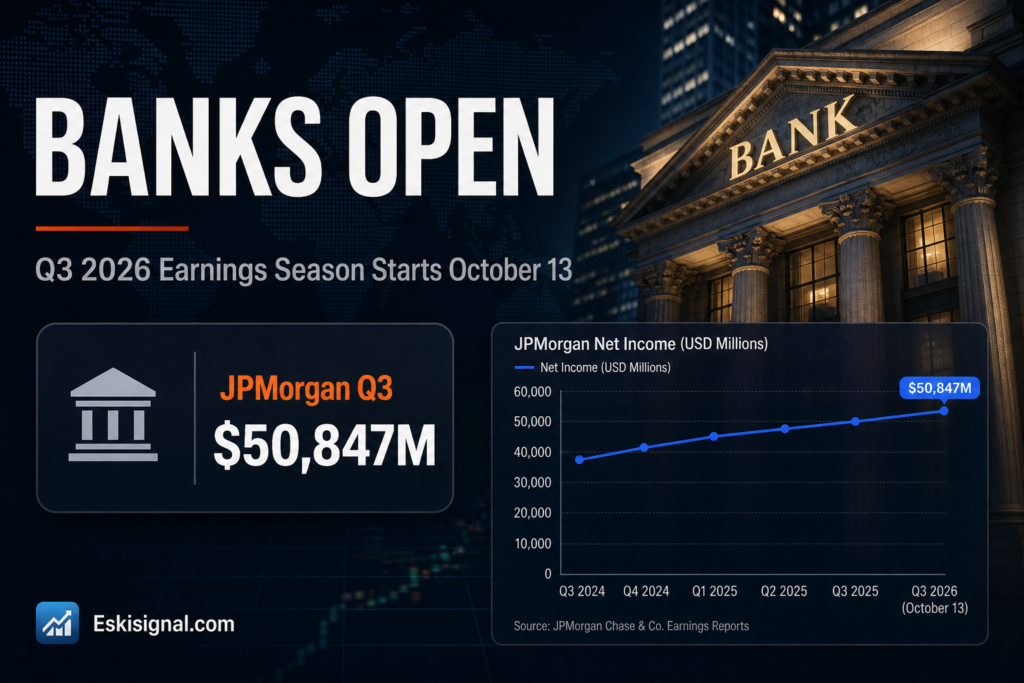
Third quarter earnings begin on October 13, when JPMorgan reports before the open and, as usual, frames how the rest of the season gets read. This quarter the bank reports into a rate-hiking cycle, a softening labour market and an energy shock — three things that show up in bank results faster than almost anywhere else in the index.
This article is for informational and educational purposes only. It is not financial advice, investment advice, or a recommendation to buy, sell, or hold any security, cryptocurrency, or financial product. Always verify data with official sources before making financial decisions.
Short answer: the calendar and why banks go first
Short answer: JPMorgan Chase is scheduled to release third quarter results around 6:45 a.m. Eastern on October 13, 2026, with its conference call at 8:30 a.m. The other large US banks follow over the same week, and the broader season runs from mid-October into mid-November. Banks report first because of their fiscal calendars, and they matter disproportionately because their results contain direct readings on consumer credit, corporate borrowing and trading activity.
| Item | Detail |
|---|---|
| JPMorgan Q3 2026 release | October 13, 2026, approximately 6:45 a.m. ET |
| Conference call | 8:30 a.m. ET |
| Consensus revenue | $50,847 million |
| Consensus EPS | $5.86 |
| Q3 2025 revenue | $47,120 million |
| Q3 2025 EPS | $5.07 |
| Q3 2025 net income | $14,393 million |
A tough comparison, by the bank’s own numbers
The year-ago quarter was strong, with capital markets activity doing much of the work. Consensus asks for roughly 8% revenue growth and about 16% EPS growth on top of it.
The gap between those two growth rates is worth noticing. EPS growing faster than revenue means the market expects some combination of margin expansion, lower credit costs and share count reduction. Share repurchases flatter EPS without improving the business, so the useful exercise on release day is checking revenue growth and pre-provision profit before reacting to the headline earnings number.
What a hiking cycle does to bank results
Rising rates affect banks through several channels that do not all point the same way, which is why “rates up, banks win” is too simple.
Net interest income generally benefits, because asset yields reprice faster than deposit costs. That advantage erodes as the cycle matures and depositors move cash into higher-yielding alternatives — the deposit beta, or the share of a rate increase that has to be passed to savers, is the number to watch and it typically rises the longer rates stay elevated.
Securities portfolios lose market value when yields rise, which can sit in accumulated other comprehensive income rather than in earnings depending on classification. It does not hit reported profit but it does affect tangible book value.
Loan demand weakens as borrowing gets more expensive, so volume growth tends to slow even as margins improve.
Credit quality is the line that matters this quarter
With payroll growth at 29,000 in September and the unemployment rate rising to 4.2%, consumer credit performance is the single most informative thing in these releases.
The specific items worth reading: net charge-off rates by segment, particularly card; the provision for credit losses and whether it rose because of actual deterioration or because of a changed economic forecast in the modelling; and early-stage delinquency rates, which lead charge-offs by several quarters and are therefore the earliest signal available.
Provisions deserve particular care. Under current accounting, banks reserve against expected losses over the life of a loan using macroeconomic scenarios. A bank can increase provisions substantially because it revised its unemployment assumption, with no change in actual borrower behaviour. The disclosure separates the two, and the distinction is routinely lost in coverage.
What the rest of the season hinges on
Three threads run through this quarter beyond the banks.
Energy costs in the cost line. Transport-intensive businesses — retailers, logistics, industrials, airlines — face diesel and jet fuel at levels that compress margins unless they can pass them on. The pass-through question gets answered company by company on these calls.
Energy producers and refiners on the other side. The same shock that hurts transport costs shows up as margin for refiners, where crack spreads have been the story rather than the crude price itself.
AI capital spending. The large technology companies report later in the month, and the question is unchanged from prior quarters: whether spending is still accelerating and what it is doing to free cash flow.
Risks, uncertainty, and limits
Reporting dates are set by companies and occasionally shift. Consensus figures move in the days before a release, and the numbers cited here reflect estimates available in early October.
Nothing in this article forecasts any company’s results or the market reaction to them. Results, guidance and credit disclosures come from company releases and filings, which are the only authoritative source.